
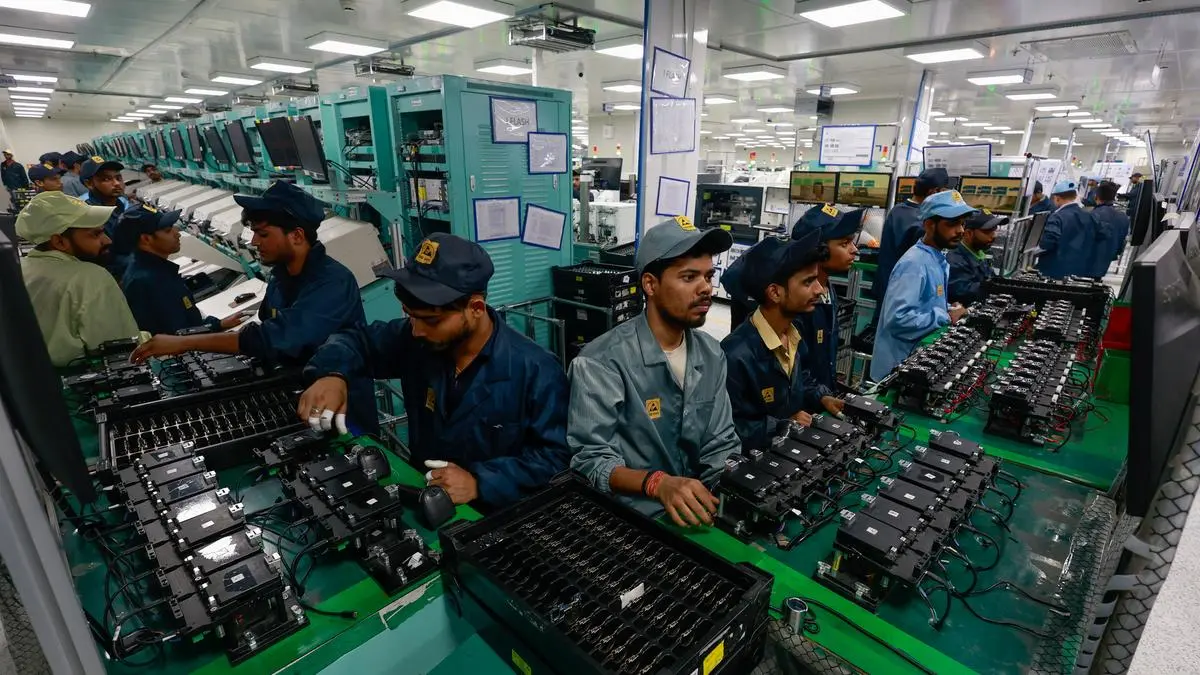
The company is pursuing a two-pronged strategy for growth: deepening relationships with existing clients through joint ventures (long-term) and focusing on tie-ups and partnerships with players across the component ecosystem to drive backward integration.
| Photo Credit:
PRIYANSHU SINGH
Shares of Dixon Technologies surged 3 per cent following 68.2 per cent y-o-y increase in consolidated net profit and a nearly 95 per cent jump in total income during the quarter ended June 2025.
Its consolidated net profit for the quarter under review stood at ₹224.97 crore as against ₹133.68 crore in the corresponding quarter previous year. The total income was recorded at ₹12,837.34 crore in June 2025 quarter as against ₹6,587.98 crore in the same quarter a year ago.
Brokerages were optimistic due to strong Q1 results, driven by the mobile and EMS (Electronics Manufacturing Services) segment. They flagged key risks such as lower-than-expected growth in the addressable market, loss of relationships with key clients, rising competition and limited bargaining power with clients, which could impact margins and overall profitability.
Domestic brokerage Motilal Oswal maintained buy and hiked the target price from ₹20,500 to ₹22,100, citing 37 per cent upward potential. It has also raised FY27 estimates by 10 per cent to factor in higher mobile volumes.
The company is pursuing a two-pronged strategy for growth: deepening relationships with existing clients through joint ventures (long-term) and focusing on tie-ups and partnerships with players across the component ecosystem to drive backward integration. Motilal believes that the approach is expected to provide greater revenue visibility and support margin improvement in the coming years.
Motilal Oswal’s report highlights that a display facility with HKC, a camera module collaboration with Qtech, and precision component manufacturing with Chongqing Yuhai Precision will enable Dixon to address a larger share of the smartphone bill of materials (BoM). Additionally, the joint ventures with Longcheer and Vivo are likely to contribute sustainable incremental volumes for the company.
Nomura retained ‘buy’ at an increased target price of ₹21,154.
HDFC Securities observed that Dixon’s growth was tempered by sluggish performance in home appliances and declines in consumer electronics and lighting segment. The analysts maintained add call at a target price of ₹17,740.
Nuvama Institutional Equities noted that Dixon is building a vertically integrated, export-oriented EMS platform to sustain growth beyond the PLI regime.
Nuvama maintains a hold rating on the stock due to its rich valuation (at a target price of ₹16,100). This cautious stance also reflects the uncertainty surrounding the approval timelines for its joint ventures, most of which are with Chinese partners.
As at 10.20 am, the stock traded 3.01 per cent positive at ₹16,597.50 (close to intraday high of 16,607.35).
More Like This
Published on July 23, 2025